A hailstorm can leave a home looking mostly unchanged from the driveway while causing damage that shortens the life of shingles, dents metal components, and creates future water-entry risks. Understanding the roof/exteriors hail damage insurance process helps you make calm, well-documented decisions before a small problem turns into a costly repair.
For homeowners in Lethbridge and Southern Alberta, timing matters. Our weather can move quickly from hail to heavy rain, high winds, and temperature swings. The goal is not to rush into a replacement or assume every mark is claim-worthy. It is to protect the property, document the facts, and work through your insurer’s requirements with a clear plan.
Start With Safety and a Ground-Level Check
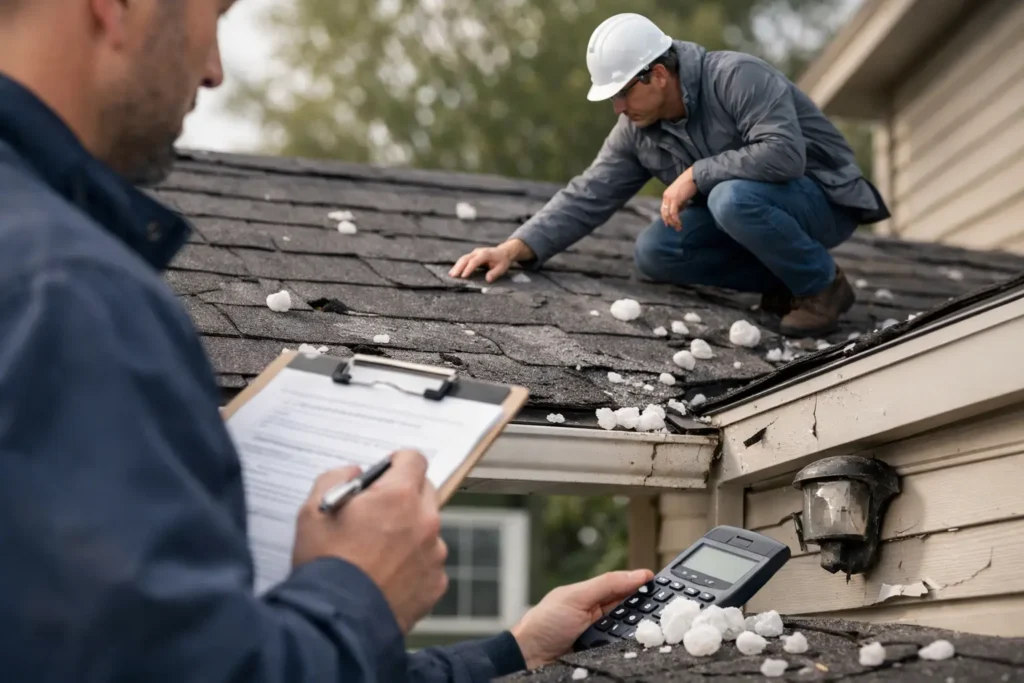
After hail, avoid climbing onto the roof yourself. Wet shingles, loose granules, and unstable ladders create unnecessary risk. Instead, walk the property from the ground and look for obvious signs such as torn or missing shingles, granules collecting near downspouts, dented gutters, damaged downspouts, cracked siding, bent fascia, or broken window screens.
Take wide photos of each side of the home, then closer photos of visible damage. If you have before-storm photos from a recent home project or listing, save those as well. They can help establish the condition of your roof and exterior before the weather event.
A professional exterior inspection is the next practical step. Hail damage is not always obvious, especially on asphalt shingles. A qualified contractor can identify impacts, collateral damage to gutters and metal flashing, and areas that may need temporary protection. An inspection also separates storm damage from normal wear, installation issues, or older maintenance needs.
Document Damage Before the Insurance Claim
Good documentation gives your claim a stronger foundation, but accuracy matters more than volume. Record the date and approximate time of the storm, keep local weather alerts if available, and make a simple written list of what you observed. Photograph damaged roofing and exterior features from safe locations, including gutters, siding, soffit, fascia, vents, fencing, and air-conditioning units where applicable.
Keep receipts for any emergency work that prevents additional damage. For example, if water enters through a storm-damaged opening, reasonable temporary measures can help protect the home. Let the insurer know about emergency repairs, and do not discard damaged materials until you have been told it is appropriate to do so.
Do not make permanent repairs before the insurance inspection unless immediate work is necessary to prevent further loss. Replacing materials too early can make it harder for an adjuster to assess the original damage. Temporary protection and permanent restoration are different decisions.
How the Roof and Exterior Hail Damage Insurance Process Works
Most homeowners insurance policies cover sudden, accidental hail damage, but coverage depends on the policy, deductible, limits, endorsements, and the age and type of materials involved. Some policies settle roof claims based on replacement cost value, while others account for depreciation or apply specific rules for older roofs. Your policy documents and insurer can clarify how your coverage works.
1. Report the Claim Promptly
Contact your insurer or broker as soon as you have a reasonable basis to believe the storm caused damage. Have your policy number, storm date, photos, and a brief description ready. The insurer will create a claim file and explain the next steps.
Be factual when describing what you see. You do not need to diagnose the roof or estimate the final cost yourself. Saying that hail struck the property and you observed dents, shingle concerns, or water intrusion is more useful than guessing at the full scope of repairs.
2. Understand Your Deductible
Your deductible is the amount you pay toward a covered loss before insurance funds apply. It is not usually something a contractor can simply remove or absorb. Any promise to “cover” a deductible through inaccurate paperwork or inflated invoices should be a warning sign.
Ask your insurer whether your policy has a standard deductible, a percentage-based deductible, or special conditions for wind and hail. Knowing this number early helps you evaluate whether a claim makes financial sense and plan for your share of the project.
3. Meet the Adjuster Prepared
The insurance adjuster evaluates the reported damage and prepares an estimate based on the policy. You have the right to be present during the appointment, and many homeowners find it helpful to have their contractor available as well. A contractor can point out roof and exterior components that may be easy to overlook, explain installation requirements, and provide a repair or replacement estimate.
The adjuster’s estimate is an important part of the process, but it may not capture every item needed once work begins. If legitimate storm-related damage or necessary code-related work is discovered later, your contractor can document it for review. Approval of additional work remains the insurer’s decision.
4. Review the Scope, Not Just the Total
When the insurer sends its estimate, read the scope of work carefully. Check that it identifies the correct roof materials, roof area, ridge caps, flashing, vents, gutters, downspouts, siding, and other affected exterior elements. A low total is not the only concern. Missing components or incorrect quantities can create problems during construction.
This is where a detailed contractor estimate is valuable. It should explain the proposed work, materials, labor, site protection, cleanup, and any items that are outside the insurance scope. Clear estimates prevent the surprise of discovering that an essential part of the repair was never included.
Choose Repairs That Protect the Whole Exterior
A hail claim may focus on the roof, but the roof is part of a connected exterior system. Damaged gutters can move water toward the foundation. Bent flashing can compromise roof transitions. Dented fascia or damaged soffit can affect appearance and ventilation. If siding is cracked or punctured, it may no longer provide the same weather protection.
The right scope depends on what was damaged and what your policy covers. Sometimes a targeted repair is appropriate. In other cases, widespread impacts or discontinued materials make replacement the better long-term choice. Your contractor should explain the trade-off plainly: repair when it restores reliable performance and matches the existing system; replace when patching leaves the home vulnerable or creates an uneven result.
Material selection also deserves attention. Southern Alberta homes need roofing and exterior products installed for high winds, hail exposure, freeze-thaw cycles, and strong sun. A claim repair is an opportunity to correct weak details, improve water management, and choose materials that support long-term durability without adding unnecessary upgrades to the claim.
Avoid Common Claim Mistakes
Storms often bring door-to-door offers from contractors who are not established in the community. A prompt inspection can be helpful, but pressure is not. Be cautious of anyone asking you to sign a contract before you understand the scope, demanding a large upfront payment, or guaranteeing that insurance will pay for a full replacement.
It is also wise not to assume every cosmetic dent requires a claim. Some damage affects appearance only, while other impacts compromise function or shorten material life. A careful inspection and an honest conversation about your deductible, policy, and long-term repair needs can prevent an unnecessary claim.
Keep communications organized in one place. Save claim numbers, emails, photos, estimates, invoices, and notes from calls with your insurer. If questions arise later, a clear record reduces stress and helps keep the project moving.
A Local Partner Makes the Process Easier
A dependable contractor should not promise an insurance outcome. What they can do is inspect the home carefully, document visible storm damage, provide a detailed estimate, communicate clearly with you, and complete approved work with durable materials and skilled craftsmanship.
HighLow Roofing & Exteriors helps homeowners look beyond the obvious roof surface to assess the exterior systems that protect their homes. The focus is straightforward: honest recommendations, clear scopes of work, and repairs or replacements built to handle Southern Alberta weather.
After the claim is settled and the work is complete, keep your final paperwork and take updated photos of the finished exterior. They are useful records for future maintenance, insurance questions, and the peace of mind that comes from knowing your home is ready for the next storm.